Hands-on travel review · Updated 22 September 2026
YouTrip Australia review: how it worked for me in China and Malaysia
I used YouTrip throughout my August trip for Alipay, WeChat Pay, contactless card payments and Grab. It became my main spending card, while a Macquarie debit card stayed in my wallet as an ATM and card-failure backup.
My verdict
Very good for travel spend
FX fee
A$0
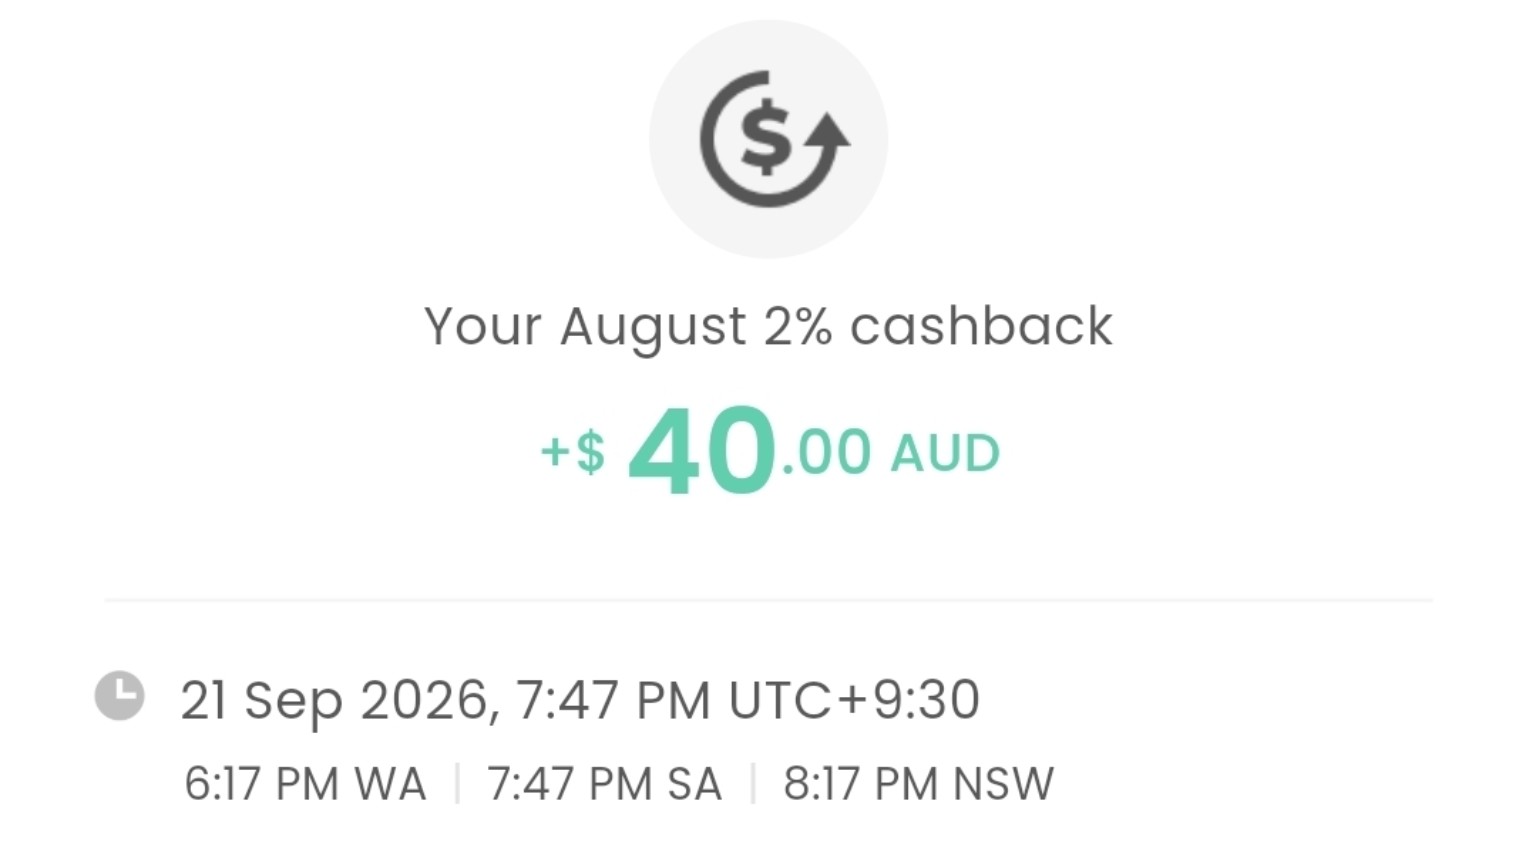
My August cashback
A$40
Best setup
YouTrip + backup card
Join through this link and get A$10 after the required first top-up steps
CheapyOZ’s featured link is shown first. Member links are checked before publication. Anyone can request a provider that is not listed yet.
The short version
YouTrip worked very well for my style of travel. In China, I linked it to both Alipay and WeChat Pay and successfully used both. Where contactless terminals were available, tapping the physical card with PayWave was easy. In Malaysia, I added it to Grab and paid without difficulty.
The strongest benefit was visibility. Every transaction triggered an app notification almost immediately, showing what I had spent in Australian dollars. That made it much easier to understand the real cost of meals, transport and shopping without manually converting every amount.
What worked in China and Malaysia
Alipay and WeChat Pay
Both worked for me in China after linking the YouTrip card. This was important because QR payments were often more useful than a physical card.
PayWave
Tap-and-pay was convenient wherever contactless Mastercard payments were accepted.
Grab in Malaysia
I added YouTrip to Grab and used it comfortably for transport and app payments.
Instant AUD notifications
The app quickly showed the Australian-dollar cost after each payment, making travel spending easier to track.
The one annoyance: frequent in-app approvals
My main frustration was that the app sometimes requested approval even for very small transactions. It occasionally made payment slower while I opened the app and confirmed the purchase.
I would prefer fewer interruptions, but this is not a deal-breaker. The extra check can help stop unauthorised card use, so the trade-off was acceptable—annoying at times, but not too bad.
Exchange rates: I spent from AUD, but you can lock a rate
I kept my balance in Australian dollars rather than exchanging in advance. YouTrip automatically converted my spending, and the final AUD amounts were generally close to the live exchange rates I checked online. They will not always match Google exactly because exchange rates move and transactions may settle at a different time.
YouTrip also lets users hold and pre-convert ten wallet currencies, including AUD, USD, EUR, GBP, JPY, NZD, SGD, CAD, HKD and CHF. If you think a rate is attractive, you can exchange in the app before travelling and lock that rate in. For other supported spending currencies, YouTrip says it automatically converts at Mastercard wholesale rates without an added FX fee.
Always choose the local currency
If a terminal or ATM asks whether you want to pay in AUD or the local currency, choose the local currency. Choosing AUD activates Dynamic Currency Conversion, where the merchant or ATM operator chooses the rate and may add a substantial margin.
Why I would avoid most airport exchange counters
I saw many travellers using physical currency-exchange counters. They may value certainty or convenience, but “no commission” does not mean the exchange is free. The provider can make money through the spread—the gap between the market rate and the less favourable rate offered to the customer.
A fair way to compare is to check how much local currency you receive after every fee. The ACCC found that airport foreign cash is generally more expensive and, in one study, buying US$200 from the cheapest non-airport supplier instead of the most expensive airport supplier saved A$40.
| Example: exchanging US$100 | Approximate value retained | Hidden cost |
|---|---|---|
| Fee-free card + fee-free ATM | Close to US$100 equivalent | About US$0–1, before rate movement |
| Counter with a 5% spread | About US$95 equivalent | About US$5 ≈ A$7 |
| Counter with a 10% spread | About US$90 equivalent | About US$10 ≈ A$14 |
Illustration only, using roughly US$1 = A$1.40 on 22 September 2026. An ATM operator fee can reduce or remove the saving, so review the ATM screen before confirming.
ATM strategy and why I carried Macquarie too
YouTrip currently includes up to A$1,500 of free overseas ATM withdrawals per calendar month. A 2% YouTrip fee applies only to the amount above that allowance, while an ATM operator may still add its own charge.
I brought a Macquarie debit card for two backup scenarios: if I exceeded YouTrip’s monthly free-withdrawal allowance and still needed cash, or if the YouTrip card did not work. Macquarie says it does not charge its own fee for overseas debit-card ATM withdrawals and has an A$2,000 daily ATM limit, although the overseas ATM operator can still charge.
My practical ATM tip
Search the ATM or bank branch on Google Maps and read recent traveller reviews. People often mention operator fees, failed foreign cards, retained cards and withdrawal limits. Prefer a bank-owned ATM in a proper branch location, decline the ATM’s currency conversion and cancel if an unexpected fee appears.
How the 2% cashback worked
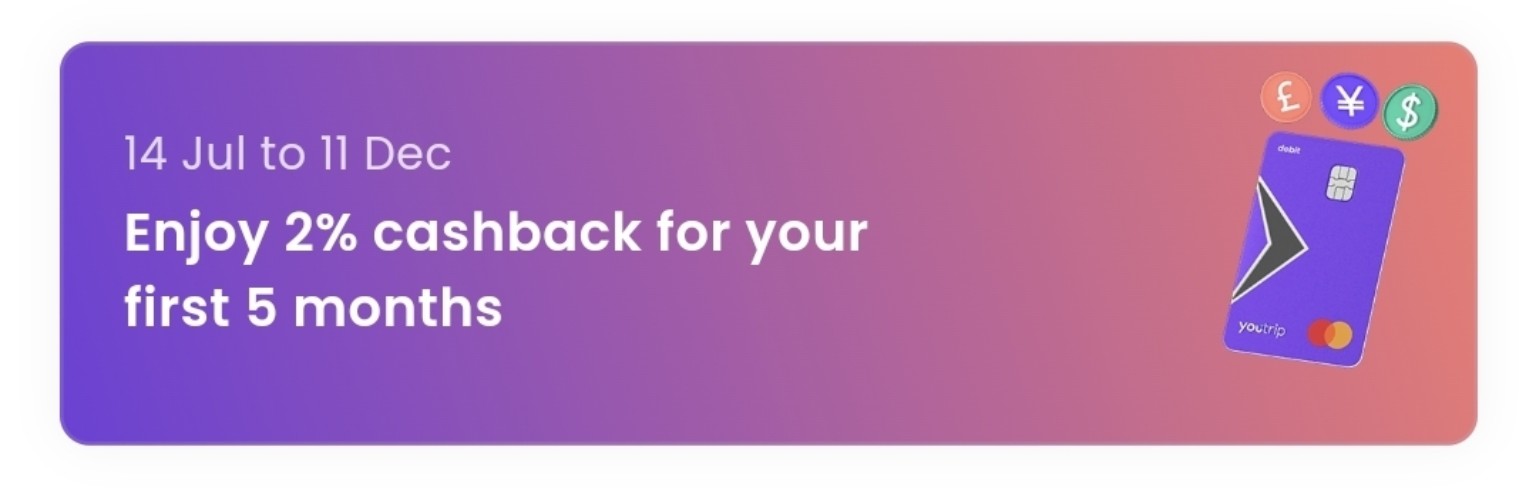
For my eligible campaign, qualifying international purchases charged in a non-AUD currency earned 2% cashback for five months. The monthly cap was A$40, so A$2,000 of eligible spending in one calendar month reaches the cap:
A$2,000 × 2% = A$40 cashback
ATM withdrawals, AUD transactions and refunded or reversed purchases did not qualify. Cashback was credited in AUD after the calendar month. My attached result shows the full A$40 for August.
That cashback made YouTrip a clear first choice for my card spending versus Wise or Revolut during the promotional period. Outside the promotion, the answer is less absolute: the best card depends on whether you need transfers, extra currencies, subscription features or larger cash withdrawals.
Pros and cons
What I liked
- • No foreign transaction fee on normal purchases
- • Worked with Alipay and WeChat Pay for me
- • Easy PayWave and Grab payments
- • Fast transaction notifications in AUD
- • Ability to pre-convert and lock supported currencies
- • Generous overseas ATM allowance
- • Excellent value while eligible for 2% cashback
What could be better
- • Small purchases sometimes required app approval
- • Never wise to rely on only one travel card
- • ATM operators may charge their own fee
- • Cashback promotion is capped and time-limited
- • Merchant and payment-platform acceptance can vary
Final verdict
YouTrip was excellent for my China and Malaysia trip. Alipay, WeChat Pay, PayWave and Grab all worked for me, the exchange rate was competitive, and instant AUD notifications made spending easy to understand. Receiving A$40 cashback for August was a genuine benefit, not just a headline offer.
I would use it again, but still carry a second fee-free debit card. My preferred setup is YouTrip for everyday foreign-currency purchases and a Macquarie debit card as an ATM and emergency backup.
Verdict: strongly recommended for Australian travellers, provided you check the current promotion and carry a backup payment method.
Frequently asked questions
Is YouTrip available in Australia?
Yes. YouTrip has an Australian product for eligible Australian residents.
Does YouTrip charge foreign transaction fees?
No foreign transaction fee is charged for normal card purchases. If you spend from AUD without pre-converting, YouTrip automatically converts supported transactions at the applicable Mastercard wholesale rate.
Is the YouTrip exchange rate good?
In my China and Malaysia transactions, the AUD amounts were generally very close to the live rates I checked online. Exact results can vary because rates move, settlement timing differs and an ATM or merchant may apply its own fee or conversion.
Can I use YouTrip in China?
Yes. I successfully used it through both Alipay and WeChat Pay, as well as contactless PayWave where accepted. Individual merchants or payment platforms can still decline a transaction.
Can I withdraw cash with YouTrip?
Yes. YouTrip currently provides up to A$1,500 of free overseas ATM withdrawals per calendar month, then charges 2% on the amount above the allowance. The ATM operator may charge separately.
Is YouTrip better than Wise or Revolut?
For my trip and while I was eligible for 2% cashback, YouTrip was my preferred spending card. It is not automatically better for everyone: Wise and Revolut have different currency, transfer, subscription and feature structures. Compare the current terms for how you travel.
How does the A$10 referral bonus work?
Open the referral link before downloading the app, complete sign-up and verification, and make the required first top-up. Under YouTrip's published referral instructions, both the new user and referrer must complete their first top-up before the A$10 rewards are credited. Confirm the offer shown on the referral screen before joining.
Is the 2% cashback capped?
Yes, for my eligible welcome promotion it was capped at A$40 per calendar month. At 2%, A$2,000 of eligible non-AUD spending reaches the monthly cap. I received the full A$40 for August. This campaign required account approval by 31 August 2026, so new applicants should check whether a replacement promotion is currently offered.